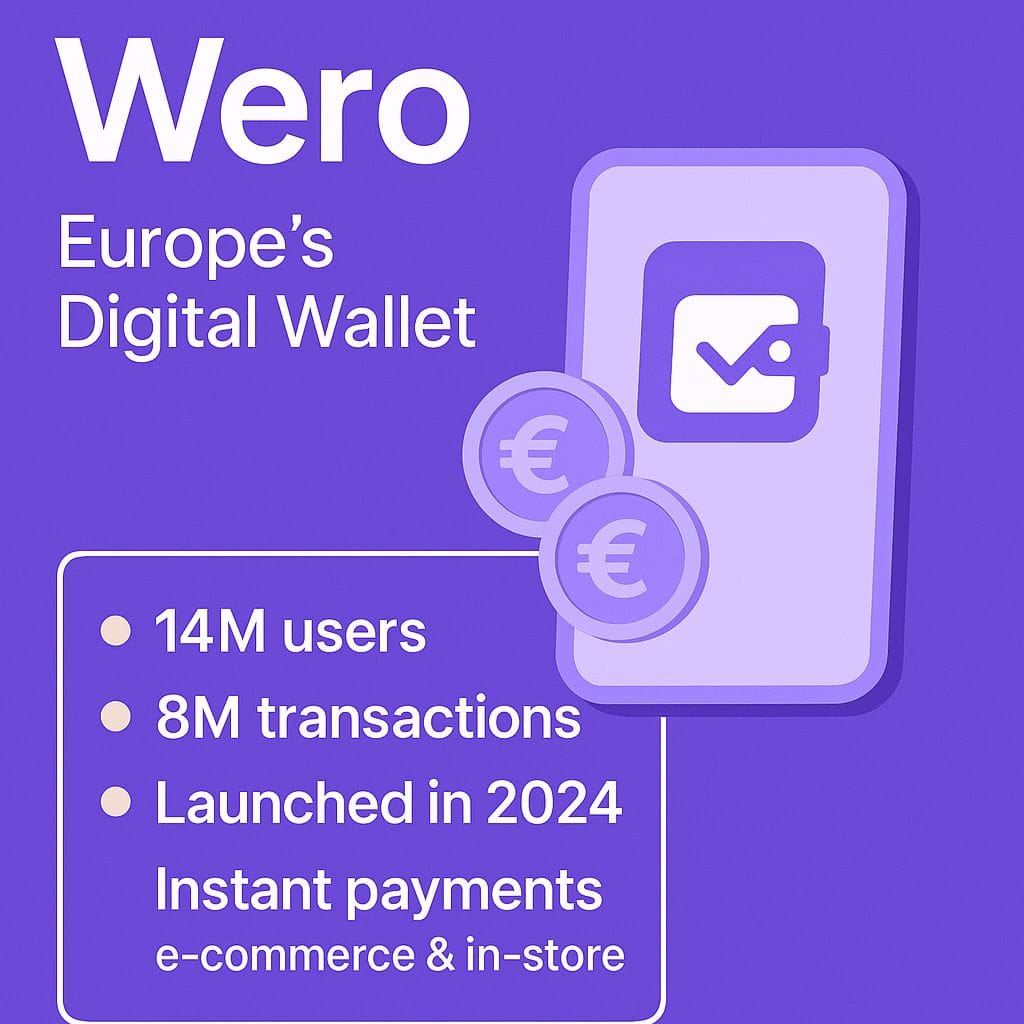
Wero is the digital wallet of the European Payments Initiative (EPI), a company owned by a group of European banks and payment providers. It lets people send and receive money, and increasingly pay online, directly from their bank account using instant transfers, without a card.
For merchants selling in Europe, Wero matters because it is taking over iDEAL in the Netherlands, is live for online payments in Germany, and is being rolled out in other markets. This guide explains what Wero is, where it works, how it compares to cards, and what merchants should do now.
Key takeaways
- Wero is a bank-backed European wallet built on instant account-to-account transfers. It launched for person-to-person payments in Germany, France and Belgium in 2024.
- Wero online payments went live in Germany in November 2025. EPI has said more countries, including Belgium, France and the Netherlands, follow in 2026.
- In the Netherlands, iDEAL is migrating to Wero, with completion targeted for the end of 2027.
- In Belgium, Bancontact Pay stays, and Wero is being offered alongside it.
- Payments come straight from the customer’s bank account, so there are no card-style chargebacks. EPI plans Wero Purchase Protection for Dutch shoppers by 2028.
What is Wero?
Wero is a mobile wallet from the European Payments Initiative. It is built on SEPA instant credit transfers: when a customer pays, the money moves from their bank account to the recipient within seconds. Customers use Wero in their own bank’s app or in the separate Wero app, depending on their bank.
EPI was set up by European banks and payment providers to give Europe its own payment method that works across borders. Wero started with person-to-person payments, where users send money with a phone number or email address, and is now expanding into online and in-store payments for merchants.
How Wero payments work
- The customer chooses Wero at checkout.
- They confirm the payment in their banking app or the Wero app, usually by scanning a QR code on a computer or being redirected on a phone.
- The money is sent as an instant bank transfer from the customer’s account.
- The merchant gets confirmation straight away.
Because the customer authenticates in their own bank, the merchant never handles card details.
Where Wero works
| Country | Status |
|---|---|
| Germany | Person-to-person payments since 2024; online payments live since November 2025 |
| France | Person-to-person payments since 2024; online payments planned for 2026 |
| Belgium | Person-to-person payments since 2024; offered to merchants alongside Bancontact Pay; online payments planned for 2026 |
| Netherlands | iDEAL migrating to Wero from 2026, with completion targeted for the end of 2027 |
Availability depends on whether the customer’s bank has joined and on your payment provider’s support, so check both for each market.
Wero and iDEAL in the Netherlands
EPI owns iDEAL and is moving it onto Wero. iDEAL | Wero co-branding launched at checkouts in 2026, Dutch banks connect to Wero from October 2026, and the migration is targeted for completion by 31 December 2027. Dutch shoppers keep paying through their own bank. EPI has said Wero scheme pricing will stay broadly in line with current iDEAL | Wero pricing until the end of 2028. More in our iDEAL guide.
Wero and Bancontact in Belgium
In Belgium, the Payconiq by Bancontact app was renamed Bancontact Pay in March 2026, with the same functions. It is not being replaced by Wero. Instead, Bancontact Company is offering Wero to former Payconiq merchants, with in-store QR codes that accept both. See our Bancontact guide.
Wero vs cards for merchants
| Wero | Cards | |
|---|---|---|
| How the customer pays | Instant transfer from their bank account, confirmed in an app | Card details, usually with 3D Secure |
| Confirmation | Instant | Authorisation instant; settlement later |
| Chargebacks | No card-style chargebacks; refunds made by the merchant | Yes, under card scheme rules |
| Coverage | Customers of participating European banks, in euros | Worldwide |
| Recurring payments | Planned, not yet available | Yes, with stored credentials |
Why merchants should pay attention to Wero
It is becoming the default in some markets
If you sell to Dutch customers, Wero is where iDEAL is going, so your checkout needs to keep up with the migration. In Germany, major retailers already accept Wero online.
Instant, final payments
Payments are confirmed straight away, which suits digital goods and services where you deliver immediately.
No card-style chargebacks
Because the customer authorises a bank transfer, there is no card chargeback process. That makes Wero attractive for merchants who struggle with friendly fraud on cards. Keep an eye on Wero Purchase Protection, which Dutch banks and payment providers plan to roll out in stages, with full coverage targeted by 1 January 2028.
Bank-backed trust
Customers pay inside their own bank’s environment, which many find more reassuring than entering card details on an unfamiliar site.
What Wero doesn’t do yet
EPI has announced plans for subscriptions, instalments, loyalty and more in-store payments, but without firm dates. Until recurring payments are available, subscription businesses still need cards or SEPA Direct Debit for renewals. See our guide to recurring billing.
How to accept Wero
- Check which of your markets Wero covers today, and which your payment provider supports.
- If you already accept iDEAL, ask your provider how it is handling the migration to Wero.
- Add Wero to your checkout through your provider’s plugin, hosted payment page or API.
- Show Wero alongside the methods your customers already use, such as cards, Bancontact or iDEAL, rather than instead of them.
Our guide to local payment methods in Europe covers the other methods in each market.
Frequently asked questions
What is Wero?
Wero is a digital wallet from the European Payments Initiative that lets people send money and pay merchants directly from their bank account using instant transfers. It launched in 2024.
Which countries is Wero available in?
Wero person-to-person payments are available in Germany, France and Belgium. Online payments went live in Germany in November 2025, with more countries planned for 2026. In the Netherlands, iDEAL is migrating to Wero.
Is Wero replacing iDEAL?
Yes. iDEAL is migrating to Wero, with completion targeted for 31 December 2027. Dutch shoppers keep paying through their own bank during the transition.
Is Wero replacing Bancontact?
No. In Belgium, the Payconiq app became Bancontact Pay in March 2026 and continues. Wero is being offered to merchants alongside it.
Can Wero payments be charged back?
Not like card payments. Wero payments are instant bank transfers the customer has approved, and refunds are made by the merchant. EPI plans Wero Purchase Protection for Dutch shoppers, with full coverage targeted by 1 January 2028.
Does Wero support subscriptions?
Not yet. Subscriptions are on Wero’s roadmap, but for now recurring payments need cards or SEPA Direct Debit.
How can a merchant accept Wero?
Through a payment provider that supports Wero in your markets. If you already accept iDEAL, ask your provider about the move to Wero.
Next step
If you sell across Europe, your checkout needs to keep up with changes like the move from iDEAL to Wero. Fasto works with adult, subscription, nutraceutical, gaming, dating and hospitality merchants, and approval typically takes two to three weeks.
Get a free quote and tell us which markets you sell to.
Sources: Wero: e-commerce live in Germany; European Payments Initiative: iDEAL to Wero migration; The Brussels Times: Payconiq by Bancontact changes its name.